How Often Should I Have My Roof Inspected?

Aaron Venegaz is the President and founder of Global Exterior Experts and has been in the construction / roofing industry for over 15+ years. He started the company back in 2010 and done everything from scheduling appointments to putting down roofs. He's also done everything from commercial roofing to residential roofing and has also worked with almost every single roofing material multiple times over the past 15 years.
Depreciation on a roofing insurance claim is the amount your insurance company subtracts from your payout because your roof was already worn before the damage happened. It reflects age, weather exposure, and normal wear. Depending on your policy, you may get that money back after the work is done (recoverable depreciation) or lose it for good (non-recoverable depreciation).
That one line on your claim paperwork can swing your payout by thousands of dollars. So let's break down how it works and what you can do about it.
RCV vs. ACV: The Two Numbers That Decide Your Payout
Every roof claim starts with two values. Once you understand them, the rest of your paperwork makes sense.
- Replacement Cost Value (RCV): what it costs to replace your roof today with similar materials, at current prices.
- Actual Cash Value (ACV): the RCV minus depreciation. In plain terms, what your worn roof was worth right before the storm.
- Depreciation: the gap between those two numbers.
Here's the thing: your policy type decides whether that gap comes back to you. A replacement cost policy usually pays ACV first, then releases the depreciation once the job is complete. An actual cash value policy pays ACV and stops there. (Check your declarations page. It's usually spelled out in the first few pages.)
How Insurers Calculate Roof Depreciation
Adjusters don't pull depreciation out of thin air. Most use estimating software built around a simple age-based formula:
Depreciation = Replacement Cost × (Roof Age ÷ Expected Lifespan)
A 10-year-old roof with a 25-year expected life shows about 40% depreciation. From there, the adjuster may adjust based on:
- Roof age (the biggest factor by far)
- Material type, since shingles, metal, and tile all wear at different rates
- Condition before the storm, like curling, granule loss, or old patches
- Maintenance history and prior repairs
- Local climate, since hot sun and freeze-thaw cycles age roofs faster
Labor is another wrinkle. Some states don't allow insurers to depreciate labor, while others do. If labor was depreciated on your estimate, ask your adjuster to explain it.
A Real-Numbers Example
Alright, let's walk through a typical roof replacement claim. These numbers are for illustration, but the math works exactly like this:
- Approved replacement cost (RCV): $18,000
- Depreciation withheld (40%): $7,200
- Deductible: $1,500
- First check (RCV minus depreciation and deductible): $9,300
- Second check (recoverable depreciation): $7,200
- Total from insurance: $16,500
- Your out-of-pocket cost: $1,500
Notice the first check covers only about half the job. That surprises a lot of property owners. It doesn't mean your claim was lowballed. It means the rest is waiting on a finished roof.
Now flip it to an ACV policy. Same storm, same roof. You'd get $9,300 and nothing more, leaving $8,700 on you. Same roof, very different bill.
Recoverable vs. Non-Recoverable Depreciation
Quick and simple:
- Recoverable: held back now, paid later once the work is done and documented. Common with RCV policies.
- Non-recoverable: gone for good. Common with ACV policies.
Worth a look: many insurers now add roof payment schedules or age-based endorsements once a roof passes 10 to 15 years. These can quietly turn an RCV policy into ACV coverage for the roof only. Read yours before storm season, not after.
The Claim Timeline: From Storm to Final Check
Every carrier moves at its own pace, but here's a realistic range for a standard shingle roof replacement:
- Report the damage: as soon as possible. Many policies require "prompt" notice.
- Adjuster inspection: usually 1 to 3 weeks after filing, longer after a big hail event.
- First (ACV) check: typically 1 to 4 weeks after approval.
- Permits and materials: 1 to 6 weeks, depending on your permit office and supply. After major storms, popular shingle colors can back-order for weeks.
- Installation: 1 to 3 days for most homes.
- Depreciation release: usually 2 to 6 weeks after final paperwork is submitted.
All in, expect about 2 to 4 months. Add time if your mortgage company is named on the check. Lenders often need to endorse insurance checks and may hold funds until they run their own inspection, which can add 2 to 4 weeks. (Who would've thought the bank would be the slowest part of a roof?)
How to Get Your Depreciation Released
Recoverable depreciation isn't automatic. Someone has to request it, and the insurer needs proof. Here's what carriers typically ask for:
- A final invoice that matches the approved scope line by line
- Completion photos of the finished roof
- A certificate of completion, if your carrier uses one
- Proof the deductible was paid, in some cases
- Permit sign-off or final inspection, where your city requires it
When we finish a roof replacement, we package these documents so the release request can go out right away. Clean paperwork means a faster check.
Where Depreciation Money Gets Lost
Of course, none of this pays out if a few things go sideways. These are the most common ways property owners lose part or all of their recoverable depreciation.
Missing the deadline. Most policies set a window to finish the work, commonly 180 days to 2 years from the date of loss. Miss it and the money can be forfeited. If you need more time, ask your carrier for an extension in writing before the deadline hits.
Partial work on a full-replacement scope. If the insurer approved a full roof and only part gets replaced, don't expect the full release.
Upgrading without a plan. Moving from standard shingles to metal or impact-resistant shingles is fine. You'll pay the price difference, and depreciation is usually released based on the original approved scope.
Cutting corners on cost. Replacement cost is generally paid up to what's actually spent on the work. A bargain job can mean a smaller release.
Code Upgrades, Supplements, and Other Surprises
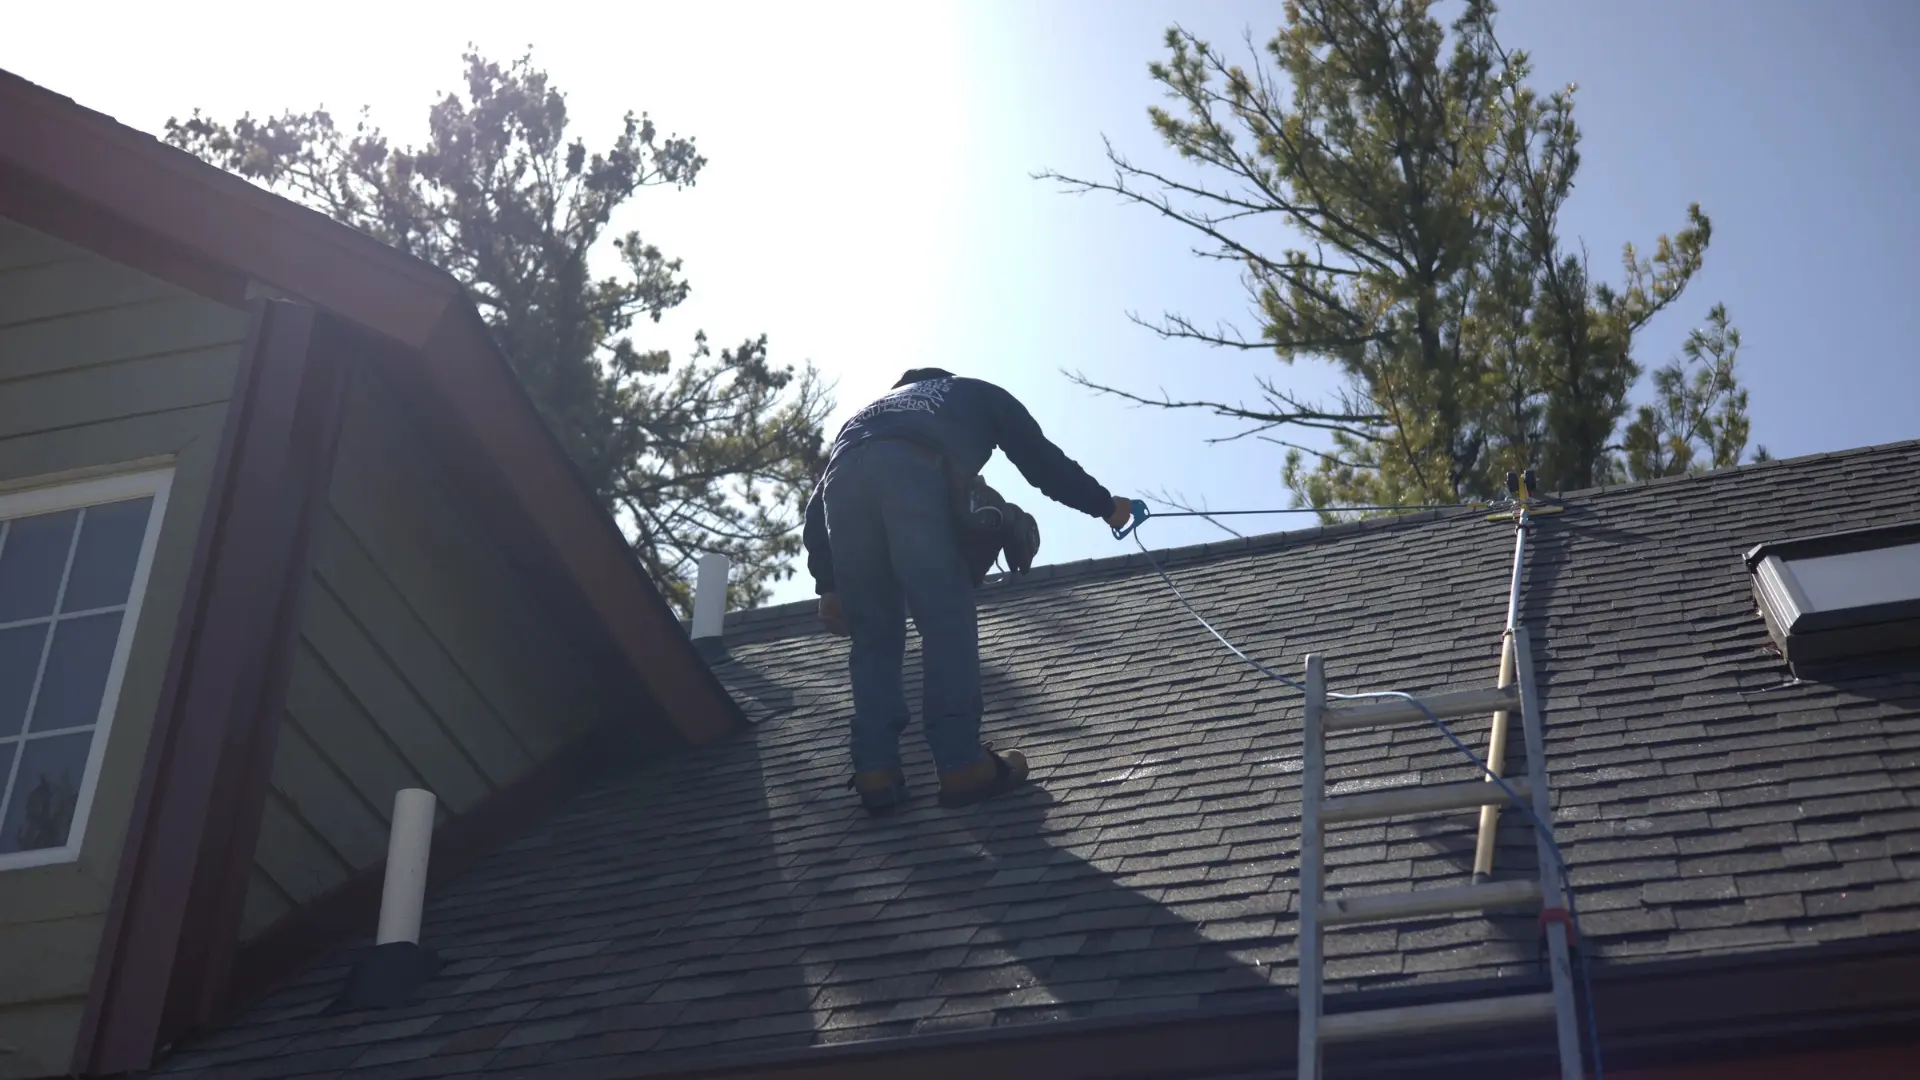
Here's where roofs get interesting. Once the old shingles come off, we sometimes find rotted decking, missing ice and water shield, or ventilation that doesn't meet current code. None of that shows up from the ground, so it's often missing from the adjuster's first estimate.
That's handled through a supplement: a request to add missed items to the approved scope. Supplements are separate from depreciation, but they raise the RCV. That means more is withheld up front and more is released at the end.
Code-required items, like drip edge or ice barrier in cold climates, often fall under Ordinance or Law coverage. Depending on your policy, these items may be paid without depreciation since they weren't part of the old roof. Decking replacement alone commonly runs about $70 to $120 per sheet installed, so it adds up fast on a full tear-off.
Summary: What to Do Next
Depreciation is the value your roof lost to age and wear, subtracted from your insurance payout. On a replacement cost policy, you can usually recover it after the roof replacement is complete. On an actual cash value policy, it's gone.
Before you sign anything or schedule work:
- Confirm whether you have RCV or ACV coverage, plus any roof payment schedule
- Find your depreciation deadline and put it on your calendar
- Compare the adjuster's estimate to a detailed inspection from your roofing company
- Keep every invoice, photo, and email tied to the claim
- Ask about Ordinance or Law coverage before tear-off day
Know your numbers, meet your deadlines, and document everything. Do that, and you'll keep the money your policy already promised you.